
a Vehicle to Transport a Family Member
As a caregiver, your responsibilities are vast, and reliable transportation is often at the top of the list. Ensuring a family member can get to medical appointments, run errands, and stay connected to the community is a crucial part of their well being. However, budgeting for a suitable vehicle can feel like a daunting task, especially when you are managing other expenses. The process involves more than just calculating a monthly payment; it requires a thoughtful look at upfront costs, ongoing maintenance, insurance, and the specific features needed for safety and accessibility. Understanding how to create a comprehensive vehicle budget tailored to your caregiving role is the first step toward finding a dependable car that fits both your needs and your finances. We are here to help you navigate this important decision with clarity and confidence, ensuring you find the right transportation solution for you and your loved one.
Finding an affordable and reliable vehicle that meets your specific caregiving needs is entirely achievable. By carefully considering the total cost of ownership beyond the sticker price, you can create a sustainable budget that provides peace of mind. Our team specializes in helping individuals in unique situations, offering flexible financing options and a wide selection of quality used vehicles. We understand the importance of your role and are committed to making the process of securing transportation as straightforward and stress free as possible for you.
A Comprehensive Guide to Vehicle Budgeting for Caregivers
Taking on the role of a caregiver is a profound commitment, and managing the logistics of transportation is a key component of that responsibility. A dependable vehicle is not a luxury; it is an essential tool for maintaining the health and quality of life for the person in your care. From critical doctor visits to simple grocery runs, mobility is freedom. This guide is designed to walk you through the specific financial considerations caregivers face when purchasing a vehicle, helping you build a realistic budget that covers every angle of vehicle ownership.
Unlike a typical car purchase, your decision is weighted with unique requirements for accessibility, space, and unwavering reliability. This changes how you should approach budgeting, shifting the focus from wants to absolute needs. We will break down the process into clear, manageable steps, from assessing your family member’s physical needs to understanding the long term financial impact of your choice. Our goal is to empower you with the knowledge to select and finance a vehicle that serves as a trusted partner in your caregiving journey. To learn more about our financing philosophy, read about what is buy here pay here financing.
Step 1: Define Your Unique Transportation Needs
Before you can even begin to think about numbers, you must first create a detailed picture of what you need the vehicle to do. A vehicle that is perfect for a daily commuter might be completely impractical for a caregiver. Start by answering a few key questions about your situation.
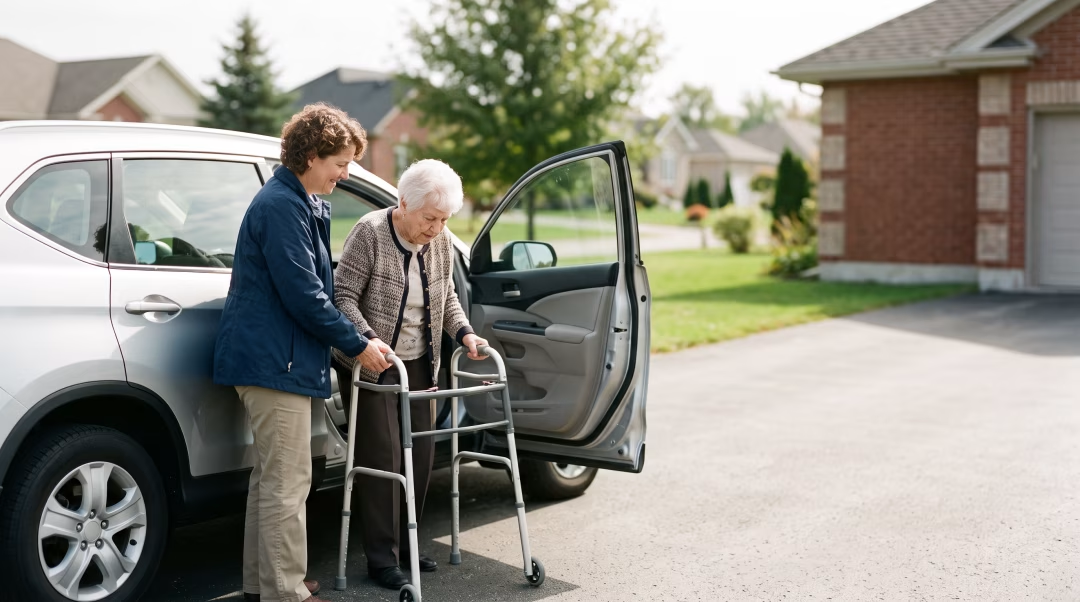
- Accessibility: How easy is it for your family member to get in and out of the vehicle? Consider factors like seat height, door opening width, and potential step in height. A crossover or minivan often provides a more accessible seating position than a low slung sedan.
- Cargo and Equipment Space: Will you need to transport mobility aids like a walker, a foldable wheelchair, or oxygen tanks? Measure these items and ensure the vehicle’s cargo area can accommodate them without sacrificing passenger space.
- Ride Comfort: A smooth, quiet ride can make a significant difference for someone who is frail or in pain. During a schedule a test drive, pay close attention to how the suspension handles bumps and road imperfections.
- Safety and Reliability: Reliability is non negotiable. You cannot risk a breakdown on the way to a critical medical appointment. Investigating a vehicle's service history and learning how do you check a used vehicle history report before buying is a vital step.
Step 2: Constructing Your Total Ownership Budget
A successful vehicle budget accounts for much more than the monthly payment. The total cost of ownership is the most accurate measure of affordability. Your budget should be broken down into two main categories: one time upfront costs and ongoing monthly expenses.
Upfront Costs
These are the initial expenses you will need to cover before you can drive the car home. Having a clear picture of these costs helps determine how much you need to save.
- The Down Payment: This is the single largest upfront cost and directly impacts your loan amount and monthly payment. A larger down payment can lower your financing charges over time. Consider reading our guide on how much should you realistically save before applying to get a better idea.
- Taxes, Title, and Fees: Sales tax, vehicle registration, and dealership documentation fees are all part of the transaction. You can learn more about what fees should you expect beyond the vehicle price to avoid any surprises.
- Initial Insurance Premium: Most insurance carriers require the first payment to be made before your policy becomes active, and you cannot finance a vehicle without proof of insurance.
Ongoing Monthly Expenses
This is the core of your long term budget. These recurring costs must fit comfortably within your overall monthly income and expenses.
- Loan Payment: This will be your most predictable expense. Our dealership offers flexible payment schedules, such as learning how weekly car payments work, which can make budgeting easier.
- Auto Insurance: The cost will vary based on the vehicle you choose, your driving record, and your coverage levels. We can provide details on what insurance coverage is typically required for our financed vehicles.
- Fuel Costs: Estimate the number of miles you expect to drive each month, including all appointments and errands. Use the vehicle’s estimated MPG to calculate a monthly fuel budget. Remember to add a buffer for fluctuating gas prices.
- Maintenance and Repairs: This is a critical and often overlooked part of the budget. For a used vehicle, it is wise to set aside at least $50-$100 per month in a dedicated savings account for routine maintenance like oil changes and tire rotations, as well as for unexpected repairs. Creating this fund is the key to preventing financial stress down the road. It's important to understand what is a reasonable emergency fund to keep after buying a car.
Step 3: Navigating Your Financing Options
A caregiver’s income can sometimes be complex, potentially including sources like disability, social security, or part time work. At our dealership, we specialize in working with diverse financial situations. We understand that a traditional credit score does not tell the whole story. We look at your entire financial picture to find a solution that works for you. Many caregivers find that fixed income sources are beneficial when applying for a loan. You can learn more about how social security income can be used to qualify on our website. The best way to start is to get pre qualified online, which gives you a clear understanding of your budget before you even start browsing our used inventory.
What type of vehicle is best for transporting someone with mobility issues?
Minivans and crossover SUVs are often the best choices for caregivers. Minivans offer sliding doors for wide, easy access and typically have a lower step in height. Crossovers provide a chair like seat height that can make it easier for someone to get in and out without having to bend down or climb up too high. Always bring your family member with you during a test drive to ensure the vehicle is a comfortable fit for them.
Can I use Social Security or disability income to qualify for financing?
Absolutely. As a Buy Here Pay Here dealership, we specialize in working with all types of income. Social Security, disability, pension, and other forms of fixed income are considered stable and reliable sources for a vehicle loan. We ask that you provide documentation, such as an award letter or bank statements, to verify the amount and consistency of the income.
How much should I set aside for unexpected repairs on a used vehicle?
A good rule of thumb is to create a dedicated savings fund and contribute between $50 and $100 per month specifically for vehicle maintenance and potential repairs. This creates a financial cushion, so an unexpected issue like a new set of tires or a battery replacement does not disrupt your overall household budget. This emergency fund is a key part of responsible vehicle ownership.
Does being a caregiver change my car insurance requirements?
While your role as a caregiver itself does not typically change your base insurance requirements, it is crucial to ensure you have adequate coverage. Because you are responsible for a vulnerable passenger, consider higher liability limits. Additionally, comprehensive and collision coverage are almost always required when you finance a vehicle, which protects your investment in case of an accident or other damage.
What is more important: a lower monthly payment or a shorter loan term?
This depends on your financial priorities. A lower monthly payment can provide more breathing room in your budget, which is often crucial for caregivers managing tight finances. However, a shorter loan term means you will pay less in total finance charges over the life of the loan and will own the vehicle outright sooner. Our finance team can show you both scenarios to help you decide which path best aligns with your long term financial goals.
By taking a thoughtful and comprehensive approach to budgeting, you can confidently select a vehicle that will be a reliable asset in your caregiving role. If you have more questions, please do not hesitate to contact us. Our team is ready to assist you every step of the way.
